Example scenario: an agency wins a fixed-fee website project with $2,500 set aside for third-party costs: premium plugins, stock photography, a form tool, a staging server and a small launch ad campaign. Costs go on the agency card. At close-out, the project lead finds $3,400 in related charges, including two plugin renewals nobody cancelled and a staging server still running six weeks after launch. The $900 overrun comes straight out of the agency’s margin.
Fixed-budget projects fail on the edges. The core work gets tracked closely, while the small external costs drift because they share a card with everything else and keep billing after the project ends. A simple fix is to give the project its own money: load the external-cost budget onto a dedicated prepaid card. This guide explains why that works, how to set it up step by step, and where its limits are.
What makes prepaid cards different
A prepaid card spends money that was loaded onto it in advance. It is not linked to a bank account and does not borrow money, which is the key difference from debit and credit cards, as the CFPB’s explainer on prepaid, debit and credit cards describes. For project budgets, that property matters more than any reporting feature: when the project money is gone, the card stops paying.
Card type
Where the money comes from
What happens at the budget line
Project fit
Company credit card
Borrowed, repaid later
Keeps paying up to the credit limit
Overruns found at month-end
Company debit card
Main business account
Keeps paying while the account has funds
Overruns hit operating cash
Prepaid card per project
Amount loaded for the project
Declines once the loaded balance is used
Overruns are blocked and visible
Five reasons the budget-to-card method works
The budget becomes physical. The card balance is the remaining budget, visible at a glance.
Overruns require a decision. Adding money is a deliberate step, usually with client or manager approval, instead of a surprise at close-out.
Every charge belongs to the project. Reconciliation is one statement, not a search across company cards.
Renewals stop at close-out. Freeze or empty the card, and forgotten subscriptions fail instead of billing for months.
Contained risk. If a vendor tied to the project has a security problem, only that card’s balance is exposed.
Step-by-step setup
Split the budget. Separate internal labor from external costs. Only external costs (tools, licenses, media, hosting, contractors’ software) go on the card.
List expected purchases. Write each one with an estimated amount, billing type (one-off or recurring) and currency.
Add a contingency line. Many teams hold back part of the external budget as contingency and load it only when needed.
Get the card and load the approved amount. Name it after the project code in your tracker.
Add the card to each vendor. One person does this, so card details are not passed around.
Track weekly. Compare the card balance with the plan in a five-minute check.
Close out. Cancel recurring tools, freeze the card, reconcile the statement and record any leftover balance.
Template: project card tracker
Column
What to record
Project code and card (last four)
Links the card to the project
Approved external budget
The total agreed with the client or sponsor
Amount loaded
What is on the card now, excluding held contingency
Planned purchases
Item, estimate, one-off or recurring
Actual charges
Date, merchant, amount
Remaining balance
From the card dashboard
Recurring tools to cancel
Tool, renewal date, cancel-by date
Change approvals
Date, who approved extra funds, amount
Close-out status
Open, closing, closed
When a prepaid project card is not the right tool
Usage-based services with unpredictable bills. If a declined payment would take a live service offline, a hard cap can do more harm than good. Keep those on a payment method with headroom and monitor them closely.
Very small projects. If external costs are one or two purchases, a separate card is more admin than it saves.
Vendors that refuse prepaid cards. Any merchant can decline a prepaid card. Check the vendor’s payment options before planning around one.
Projects where the client pays vendors directly. Then the costs never touch your books at all.
Close-out checklist
Cancel every recurring tool or transfer it to the client’s account.
Download the card statement for the project file.
Match each charge to a planned purchase or an approved change.
Freeze the card so nothing else can charge it.
Record the leftover balance and decide whether to reuse the card for the client’s next project or keep it frozen.
Note what went over or under plan to improve the next estimate.
Worked example with Vizovcc
Vizovcc is one provider that fits this method. It sells prepaid virtual Visa and Mastercard cards that you buy from an account balance funded with crypto, such as USDT, USDC, Bitcoin or ETH. There is no credit line and nothing to repay. Each card has a fixed price shown on its card page, part of which is the issue charge, with the rest loaded onto the card as spendable balance.
Take the website project above. The agency buys one Vizovcc card sized to the approved external budget and records its last four digits under the project code. The project lead adds it to the plugin store, the stock photo site and the hosting provider. Weekly, they compare the dashboard balance with the plan. At launch plus two weeks, they cancel recurring tools and freeze the card from the dashboard. Any renewal that slipped through the checklist will be declined instead of billed to the agency.
Some limits apply. Vizovcc has no sub-accounts or team roles, so whoever signs in sees every project’s card, and the login should stay with one person. You cannot set merchant locks or custom spend limits on a card: the loaded balance is the cap. Card balances are not refundable once purchased, so size the card to the budget rather than buying a large card for a small project. Cards are often ready within minutes, and each vendor decides whether it accepts them, so test early in the project, not on launch day.
Frequently asked questions
Should each project have its own card, or each client?
Per project is cleaner for fixed-fee work. Per client suits retainers where costs roll from month to month.
What if the project needs more money mid-way?
Treat it as a change request. Get approval, record it in the tracker, then add funds. The extra step is the point.
Can I reuse a card after the project ends?
Yes, if it has a leftover balance and the next project is for the same client. Otherwise keep it frozen so old vendors cannot charge it.
What about projects billed in different currencies?
Note each vendor’s billing currency in the tracker. If most project costs bill in one currency, a card in that currency avoids conversion on every charge. Check the currency on the card page before buying, and keep a small margin in the balance for any conversion differences.
Who should hold the card details?
One person, usually the project lead or the finance owner. They add the card to each vendor directly, so the number never sits in chat threads or shared documents.
Key takeaways
Fixed-budget projects overrun on small external costs that share a company card.
A prepaid card loaded with the external budget makes overruns visible and blocks them by default.
Track weekly, treat top-ups as change requests, and freeze the card at close-out.
Keep usage-based critical services off hard-capped cards.
Check vendor acceptance early; any merchant can decline a prepaid card.
Pick your next fixed-fee project and run its external costs through a dedicated card from kickoff to close-out. If you want a prepaid option funded with crypto, look at Vizovcc and match a card to the project’s approved budget.
Example scenario: you are about to start a $20-a-month design tool. Your bank app offers to create a virtual debit card in seconds. Your credit card issuer has a “virtual number” button too. A colleague swears by prepaid virtual cards for anything that renews automatically. All three would get you through the checkout, but they behave very differently when a charge goes wrong, when a renewal fails or when the merchant gets breached.
The words “virtual debit” and “virtual credit” are used loosely in marketing, which makes the choice harder than it should be. This guide explains what separates the three card types, compares virtual debit vs credit card protections side by side, and gives you a short framework for deciding which card belongs on which online account.
The short answer
“Virtual” only describes the format: a card number, expiry date and security code that live in an app or dashboard instead of on plastic. What matters is where the money comes from.
A virtual debit card spends money straight from your bank account.
A virtual credit card borrows against a credit line that you repay later.
A prepaid virtual card spends a balance you loaded in advance and stops when that balance runs out.
Everything else, from fraud protection to the effect on your credit file, follows from that difference.
What each card type is
Virtual debit card
A virtual debit card is a second card number linked to your current or checking account. Many banks and neobanks let you create one in their app, sometimes with an option to delete and replace it. Every purchase reduces your account balance immediately, so there is no bill to pay later. The trade-off is that a fraudulent charge also comes out of your real money right away, and you wait for the bank to investigate before it comes back.
Virtual credit card
A virtual credit card is a card number tied to a credit card account. Some issuers let you generate extra numbers for online shopping that all bill to the same credit line. You need to qualify for the credit account first, which usually involves a credit check, and you repay what you spend by the due date. As the CFPB’s explainer on prepaid and credit cards puts it, using a credit card means borrowing money, and carrying a balance means paying interest.
Prepaid virtual card
A prepaid virtual card is not linked to a bank account or a credit line. You load it with money first, then spend up to that balance. Some prepaid cards can be reloaded and some are used until empty. Because there is no borrowing, there is usually no credit check, and the card cannot take more than what is on it. That same feature can cause a renewal to fail if you forget to keep the balance topped up.
Virtual debit vs credit vs prepaid: side-by-side comparison
Feature
Virtual debit card
Virtual credit card
Prepaid virtual card
Where the money comes from
Your bank account
A credit line you repay
A balance you load first
Usually needs
A bank account with that bank
Credit approval and a bank account to repay from
Funding for the balance; requirements vary by provider
Can you spend more than you have?
Only if overdraft is enabled
Yes, up to the credit limit
No, spending stops at the balance
If a fraudulent charge hits
Your own money is gone until the bank refunds it
The charge sits on the issuer’s money while you dispute it
Loss is limited to the balance on that card
Effect on your credit file
None
Builds or harms credit history
None
Interest
None
Charged if you carry a balance
None
Best online use
Everyday purchases from trusted stores
Large purchases, travel bookings, disputes-heavy categories
Subscriptions, trials, unfamiliar merchants, separate budgets
A note on fraud rules
Protection depends on where you live and who issued the card. In the US, federal rules cap your liability for unauthorized credit card charges at $50. Debit card liability depends on how fast you report: up to $50 if you report within two business days, up to $500 after that, and potentially more if you wait beyond 60 days after the statement arrives. Many banks voluntarily offer zero-liability policies on top of this. Since April 2019, the CFPB’s prepaid rule has given many registered prepaid accounts in the US similar error and theft protections. Outside the US, the rules differ by country, and providers often set their own policies, so read the terms before you rely on a card for anything expensive.
Where each card wins online
Use a credit card when the purchase is large or risky to deliver
Flights, hotels, electronics and anything that might not arrive are classic credit card territory. If something goes wrong, the disputed money is the issuer’s, not yours, and you may earn rewards on the purchase. The catch is discipline: interest wipes out any rewards quickly if you do not pay in full.
Use a debit card for routine purchases from merchants you trust
A virtual debit card is convenient for regular shopping from established stores. It avoids interest and keeps spending tied to money you have. Avoid putting it on dozens of small sites, because every site that stores the number is another place it can leak from, and a leak hits your main account.
Use a prepaid card to contain risk and budgets
Prepaid virtual cards work well for subscriptions you want to cap, free trials you might forget, new merchants you do not fully trust yet and separate budgets such as a project’s tool costs. The worst case is losing the loaded balance, not your salary. They also help people who cannot get a credit card, or whose local bank card is declined by foreign merchants.
A five-question decision framework
Could this purchase go wrong in a way you would need to dispute? If the amount is large and the delivery is uncertain, lean toward credit.
Will the merchant store your card and charge it again? For recurring billing, a separate prepaid or virtual card limits what a breach or an unwanted renewal can take.
Do you want the spending to stop at a fixed amount? Prepaid cards stop at the balance. Credit and debit cards do not, unless your bank offers spending limits.
Does the merchant accept the card type? Some merchants decline prepaid cards, and some subscription and cloud providers restrict them. Check the merchant’s billing help page before you commit.
Do you need to build credit history? Only a credit card does that. Debit and prepaid cards do not appear on your credit file.
Three common misconceptions
“Virtual credit card” always means credit. Many products sold under that search term are prepaid or debit cards. Check whether there is a credit line, a repayment date and interest. If there is not, it is not a credit card.
Virtual cards are always single-use. Some issuers offer disposable numbers, but many virtual cards are ordinary reusable cards that simply have no plastic.
A prepaid card is the same as a gift card. Prepaid network cards can often be reloaded and used anywhere the network and merchant accept them. Gift cards are usually tied to one store or ecosystem.
A prepaid example: how Vizovcc fits
To see what the prepaid column looks like in practice, take Vizovcc, a service that sells prepaid virtual cards. There is no credit line and nothing to repay. You add crypto such as Bitcoin, USDT, USDC or ETH to an account balance, then buy cards from that balance. Signing up needs an email address, and you do not need a bank account to fund it.
Each card has a fixed price on its card page, and the page shows how that price splits between a card issue charge and the balance loaded onto the card. Card details appear in the dashboard once the card is ready, often within minutes, though some cards are prepared by the team after purchase. The catalog covers prepaid Visa, Mastercard, American Express, Maestro, JCB and UnionPay cards, including US-issued cards and local-currency cards for a range of countries. Its prepaid Visa and Mastercard virtual cards are the general-purpose options.
Several features map directly to the prepaid strengths above:
Several cards per account from one balance, so subscriptions or projects can each have their own card.
Each card has its own balance, which caps what any one merchant can charge.
Freeze and unfreeze from the dashboard.
3D Secure support, and card pages that show Apple Pay and Google Pay compatibility.
The limits matter just as much. Vizovcc funding is crypto only, so it suits people who already hold crypto. Like every prepaid card, acceptance varies: each merchant decides which cards it takes, and any of them can decline a prepaid card. Card purchases are final, so pick the card and currency carefully. And because it is prepaid, it will not build credit history or give you the dispute cushion of a credit card.
FAQ
Is a virtual debit card safer than a virtual credit card?
Not by default. A virtual debit number hides your main card number, but a fraudulent charge still drains your bank account until it is refunded. A credit card keeps the disputed money off your account. A prepaid card limits the loss to its balance.
Do prepaid virtual cards affect my credit score?
No. Prepaid cards involve no borrowing, so they are not reported as credit. They neither help nor hurt your credit history.
Why do some websites decline prepaid cards?
Merchants set their own payment rules. Some decline prepaid cards to reduce fraud or because they bill in arrears and want a card that can cover a variable bill. Always check the merchant’s payment help page first.
Key takeaways
“Virtual” describes the format. Debit, credit and prepaid describe where the money comes from.
Credit cards give the strongest dispute position for large or risky purchases, but cost interest if you carry a balance.
Debit cards suit routine purchases from trusted stores, and a leak hits your main account.
Prepaid cards cap losses and budgets, which makes them a good fit for subscriptions, trials and new merchants.
Check merchant acceptance before you choose a card type for any recurring bill.
A practical setup for most people is a mix: credit for big purchases, debit for everyday stores and a prepaid card for everything that renews on its own. If you want to try the prepaid side with crypto funding, compare the card pages at Vizovcc and start with one card for your most important subscription.
Here is a typical example. An operations manager gives the design tool a virtual card with a $30 monthly limit, because the plan costs $30. Three months later the vendor adds sales tax at checkout, the renewal comes to $32.40, and the card declines it. The workspace drops to read-only on a Monday morning, two designers lose access to client files, and someone spends an hour finding out why.
The opposite mistake is just as common. A team sets a generous limit “to be safe”, an annual upgrade goes through by accident, and nobody notices a $600 charge until the statement arrives. A good virtual card spending limit sits between those two failures: high enough that every legitimate renewal clears, low enough that anything unexpected is blocked. This guide explains the limit types providers offer, a simple formula for sizing them, and how to handle a card that has no adjustable limit at all.
How virtual card limits work
A spending limit is a rule the card issuer checks when a merchant asks to authorize a payment. If the amount fits inside the rule, the authorization is approved. If it does not, the issuer declines it before any money moves. The merchant only sees a decline, not the reason, which is why a limit that is a little too tight looks to the vendor like a failed card.
Providers describe their limits differently, so read the details before you rely on one. Privacy.com, for example, lets users set limits per transaction, per month, per year or as a total, and says a transaction that goes over the limit is declined straight away. Other providers reset monthly limits on a calendar date or on a rolling window. That difference matters if your vendor bills on the 30th and the window has not reset yet.
The main limit types
Limit type
What it blocks
Best for
Watch out for
Per-transaction limit
Any single charge above the amount
Fixed-price monthly plans
Annual renewals and one-off seat additions fail
Monthly (recurring) limit
Total spend above the amount in one period
Subscriptions with occasional add-ons
Calendar resets versus rolling windows
Total or lifetime limit
All spend once the total is reached
Trials, one-off projects, fixed budgets
The card stops for good when the total is used
Prepaid balance
Any charge larger than the funds on the card
Hard ceilings without settings to manage
You can’t fine-tune it, and renewals fail once funds run low
Limits inside the platform
Spend the platform itself stops or flags
Ad accounts, cloud and API usage
Some only send alerts and never stop charges
Limits inside platforms are a separate layer
Many platforms let you cap spend before it ever reaches the card. Meta’s account spending limit pauses every ad in the account once it is reached, and the amount spent toward it does not reset by itself at month end; you reset it manually, as Meta’s help page on resetting the account spending limit explains. Cloud budgets work differently. According to AWS’s budgeting best practices, the billing data behind AWS Budgets is updated at least once per day, so an alert can arrive after the spend has already happened. A card limit is the backstop behind these tools, not a replacement for them.
A sizing formula that works for most renewals
For a fixed-price subscription, set the limit to the plan price, plus any tax the vendor adds, plus a small buffer. Each part covers a specific way renewals fail.
Plan price: the amount on your latest invoice, not the price on the marketing page. Seat counts, add-ons and discounts change it.
Tax: VAT, GST or sales tax depends on where your business is registered and where the vendor collects tax. Check a real invoice to see whether tax is added on top of the listed price.
Currency buffer: if the card is in one currency and the vendor bills in another, the converted amount moves with the exchange rate every month.
Price-change buffer: vendors raise prices, usually with notice by email. A buffer gives you one renewal cycle to react instead of a surprise decline.
Worked example (illustrative numbers): a $20 monthly plan with 20% VAT added at checkout comes to $24. Add a 10% buffer and the limit is about $26.40. Round to $27. A renewal at the normal price clears, a moderate price rise clears, and an accidental annual plan at $240 is blocked.
Usage-based tools need a different rule
Cloud hosting, AI APIs and ad platforms bill on usage, so there is no fixed price to start from. For these, base the limit on your highest normal month over the last quarter, add headroom for growth, and set the platform’s own budget alert well below the card limit. The alert tells you spend is climbing. The card limit stops the extreme case, such as a leaked API key or a runaway job.
Annual plans and verification charges
Annual renewals are the most common cause of “the limit worked for a year, then failed”. Put a calendar reminder two weeks before each annual renewal and check the limit then. Also expect small verification charges when you first add a card. Google, for example, often places a small charge to check a new card, and it can be declined if the funds or billing details are wrong.
Step-by-step: setting limits across your subscriptions
Export every recurring charge from the last 12 months of card and bank statements. Note the vendor, amount, currency and billing frequency.
Sort vendors into three groups: fixed monthly, fixed annual and usage-based.
Give each vendor its own card where you can. A limit only makes sense when one card pays one vendor.
Apply the formula to fixed plans: invoice amount, plus tax, plus a 10 to 15% buffer.
Set usage-based limits from your highest recent month plus headroom, and turn on the platform’s own alerts below that line.
Copy billing details exactly as the card provider shows them. A name or address mismatch causes declines that look like limit problems.
Test with the first charge. Watch the first renewal on each new card and adjust before the second one.
Review quarterly. Seat changes and price rises add up, and a limit set a year ago is often wrong today.
When a renewal still fails
If a renewal declines, check the cause before raising the limit. Limits are only one of several reasons a card payment fails. Others include an incomplete 3-D Secure check, a billing name or address mismatch, an expired card and the merchant’s own risk checks. Raising a limit to fix a billing-address problem only removes the protection you set up.
What if your card has no adjustable limit?
Not every virtual card provider offers spend controls. Some cards are prepaid, which means the ceiling is the money on the card rather than a setting you choose. That is a blunter tool, but it still gives you a hard stop.
ZenVCC is an example of this model, and it is worth being clear about what it does and doesn’t do. ZenVCC does not offer per-card spend limits, merchant locks or a card freeze. You fund one account balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), then buy separate prepaid Visa, Mastercard, American Express or Maestro cards from that balance. A charge larger than a card can cover is declined as insufficient balance, and cards can’t be topped up from the dashboard, so the prepaid amount is the ceiling.
Used with the advice above, that structure still covers the main goals:
One card per vendor. Each subscription has its own card, so one vendor’s overcharge can’t drain the card paying for another tool.
No overspending past the balance. Prepaid funds can’t be exceeded, which suits teams that want a hard stop without managing limit settings.
Budgets set inside each platform. ZenVCC leaves budgets to the platforms themselves, which is where the account spending limits and alerts described earlier live.
Predictable card costs. Each card has a one-time $10 issue fee, each payment costs $0.10, and there is no monthly fee.
Fewer card swaps. Cards are valid for three years from the day they are ready, and if a card can’t be prepared, the full amount, issue fee included, goes back to your balance.
The trade-off is flexibility. If you need to raise a limit by a few dollars before tomorrow’s renewal, a card with adjustable controls is easier. If a prepaid card is running low ahead of a renewal, plan to move that vendor to a new card in time. The cards also can’t complete a payment that asks for a 3-D Secure code, because the dashboard doesn’t show those codes, so check whether a vendor requires that step. ZenVCC’s guide to why card payments get declined covers the common causes and what to check first.
Common mistakes
Setting the limit to the exact list price. Tax, currency movement and price changes push real charges above it.
Sharing one limited card across several vendors. The first vendor to bill uses up the room, and the others decline.
Forgetting annual renewals. A monthly-sized limit will block the yearly charge.
Relying on platform alerts alone. An alert that arrives the next day does not stop a charge that already happened.
Using limits to avoid a vendor’s terms. A declined renewal does not cancel a contract. Cancel inside the vendor’s account, and treat the card limit as a safety net.
Key takeaways
Size fixed-plan limits as invoice amount plus tax plus a 10 to 15% buffer.
Base usage-based limits on your highest normal month, with platform alerts set below the card limit.
One card per vendor is what makes any limit useful.
Check annual renewals and verification charges before they hit.
A prepaid card works as a fixed ceiling even when there is no limit setting to adjust.
Start with your five most expensive subscriptions this week: put each on its own card, apply the formula and note the next renewal dates. If you prefer prepaid cards with no monthly fee as the ceiling behind your platform budgets, take a look at ZenVCC and see whether its model fits your stack.
Elegant Charters, a Perth-based chauffeur and transportation provider, has announced the introduction of Swan Valley Tours, expanding its travel and sightseeing services for residents, visitors and groups exploring one of Western Australia’s recognised tourism destinations.
The new service provides an additional transportation option for travellers seeking to explore the Swan Valley region with private chauffeur-driven transport. The offering builds on Elegant Charters’ existing services across Perth, including airport transfers, corporate transportation, private tours, event travel and group transfers.
Supporting a Growing Demand for Flexible Regional Travel
The Swan Valley is a popular destination for visitors interested in Western Australia’s food, wine, culture and regional attractions. Exploring the area can involve travelling between multiple destinations, making convenient and reliable transportation an important consideration for individuals, families and groups.
Travellers may also prefer alternatives to self-driving, particularly when planning visits to wineries, restaurants and other hospitality venues.
Elegant Charters’ introduction of Swan Valley Tours responds to this travel requirement by extending its chauffeur transportation services beyond conventional point-to-point transfers.
A Chauffeur Service Designed Around Passenger Requirements
Through its new Swan Valley Tours offering, Elegant Charters aims to provide travellers with convenient transportation for exploring the region according to their travel preferences.
The company’s vehicle fleet includes sedans, SUVs, vehicles accommodating four to seven passengers, and minibuses and maxi cabs with capacities ranging from 13 to 24 passengers.
This range allows the company to accommodate different travel requirements, including private journeys, family outings and larger group transportation.
Depending on individual arrangements, travellers can organise transportation for regional sightseeing, hospitality visits, special occasions and group excursions.
The service also draws on the company’s established booking and customer support arrangements, including 24-hour availability, online reservations and personalised travel planning.
Connecting Perth Transportation With Regional Tourism
The introduction of Swan Valley Tours represents an extension of Elegant Charters’ broader transportation services in Western Australia.
In addition to sightseeing transportation, the company provides Perth Airport transfers, hotel transportation, corporate travel, wedding transportation, cruise transfers, FIFO journeys and long-distance private transfers.
Its fleet options are intended to serve different passenger requirements, from individual travellers requiring private chauffeur services to families and larger groups needing coordinated transportation.
The company also offers baby-seat options for families travelling with young children, along with flexible payment arrangements and online booking facilities.
Exploring the Swan Valley
Located northeast of Perth, the Swan Valley offers visitors a range of experiences, including wineries, local food producers, restaurants, cultural attractions and regional hospitality venues.
A private tour arrangement can provide travellers with greater flexibility when planning their visits, particularly when multiple destinations are included in one journey.
For visitors arriving in Perth, combining regional sightseeing with professionally arranged transportation may also simplify travel planning and reduce the need to organise separate transport arrangements.
Elegant Charters’ new service adds another option for travellers looking to experience the region while travelling from Perth and surrounding suburbs.
Company Background
Elegant Charters provides chauffeur-driven transportation and private transfer services throughout Perth and surrounding areas. Based in Southern River, Western Australia, the company serves individuals, families, business travellers and groups with a range of passenger transportation options.
Its services include airport transfers, private chauffeur bookings, corporate travel, sightseeing tours, wedding transportation, event transfers, FIFO transport and long-distance journeys.
The company operates a fleet comprising sedans, SUVs, multi-passenger vehicles and minibuses, with options designed to accommodate different passenger numbers and travel requirements.
Through its online booking platform, customers can request quotes and organise transportation for planned journeys, with 24-hour booking availability.
Executive Comment
Suggested executive quote for approval:
“Introducing Swan Valley Tours allows us to extend our transportation services to travellers who want a convenient and comfortable way to explore the region. We recognise that every journey has different requirements, whether it involves a private outing, a family trip or transportation for a larger group. Our focus is on providing flexible travel arrangements supported by professional chauffeur services,” said a spokesperson for Elegant Charters.
Looking Ahead
Elegant Charters plans to continue developing its transportation and private travel offerings to address the changing requirements of Perth residents, tourists and business travellers.
The addition of Swan Valley Tours reflects the company’s broader focus on providing transportation solutions for both everyday journeys and regional travel experiences.
Travellers interested in arranging chauffeur-driven transportation or requesting information about Swan Valley Tours can visit the company’s website.
About Elegant Charters
Elegant Charters is a Perth-based chauffeur and transportation service provider operating from Southern River, Western Australia. The company offers airport transfers, private chauffeur services, corporate transportation, sightseeing tours, wedding transfers, event transportation and group travel.
Its fleet includes sedans, SUVs, multi-passenger vehicles and minibuses, with transportation options for individuals, families and larger groups. Elegant Charters also provides personalised travel arrangements, 24-hour online booking availability and transportation services across Perth and surrounding regions.
Media Contact
Company: Elegant Charters – Airport Transfers Perth – Chauffeur Service Perth Location: Southern River, Western Australia, Australia Phone: +61 458 655 640 Website:https://elegantcharters.com.au/
Valentine Services – Stump Grinding has announced municipal stump grinding services in Cincinnati, Ohio, expanding its stump removal capabilities to address the maintenance needs of public properties, municipal facilities and other community spaces. The service focuses on removing unwanted tree stumps and surface roots that can create maintenance challenges, interfere with landscaping and present potential tripping hazards.
Municipal property maintenance departments regularly manage trees across parks, public grounds, landscaped areas and other shared spaces. Following tree removal, remaining stumps can complicate mowing, restrict landscaping improvements and create obstacles for pedestrians and maintenance crews. Professional stump grinding provides municipalities with an option for addressing these concerns without requiring complete excavation of every stump.
Addressing Stump-Related Challenges in Public Spaces
Unremoved tree stumps can become ongoing maintenance concerns for local governments and public property managers. Beyond affecting the appearance of public grounds, exposed stumps and surface roots can interfere with routine groundskeeping and limit the usability of outdoor spaces.
In areas with regular pedestrian activity, deteriorating stumps and exposed roots may also contribute to trip hazards. Removing these obstacles can support broader property maintenance efforts and help municipalities maintain accessible, usable outdoor environments.
Municipal stump grinding offers an approach for addressing these issues while reducing the disruption that can accompany more extensive stump excavation work.
Company Expands Services to Support Municipal Property Maintenance
Valentine Services – Stump Grinding provides stump grinding and removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company’s municipal service offering extends its existing residential and commercial capabilities to public properties and municipal maintenance needs.
The company works to remove unwanted stumps, manage surface roots and clean up grinding debris. Its approach is designed to accommodate different stump sizes and property conditions, including locations where surrounding landscaping and access considerations require attention.
By extending its services to municipal properties, Valentine Services aims to provide another resource for public works departments, municipal contractors and property maintenance teams responsible for maintaining community spaces.
Municipal Stump Grinding Services and Capabilities
Valentine Services – Stump Grinding offers several services relevant to municipal property maintenance and groundskeeping projects, including:
Municipal stump grinding: Removal of unwanted tree stumps from public grounds and other municipal properties.
Surface root grinding: Addressing exposed roots that may interfere with mowing, landscaping and pedestrian use.
Large stump removal: Grinding larger stumps resulting from tree removal projects.
Grinding debris cleanup: Managing wood chips and debris generated during stump grinding.
Site restoration: Preparing completed grinding areas for subsequent landscaping and property maintenance.
Project requirements can vary depending on stump size, site conditions, equipment access and surrounding infrastructure. Municipal departments and contractors can contact the company to discuss project details and request an estimate.
Supporting Cincinnati and Northern Kentucky Communities
Valentine Services – Stump Grinding serves Cincinnati and surrounding communities, including Blue Ash, Mason, West Chester, Fairfield, Loveland and Hamilton in Ohio.
Its Northern Kentucky service area includes Florence, Covington, Erlanger, Burlington and Hebron, along with nearby communities.
The company’s service coverage supports residential customers, commercial property owners, property managers and contractors seeking professional stump grinding and removal services.
As municipalities continue to maintain public landscapes and outdoor facilities, stump removal remains one component of broader tree management and grounds maintenance programs.
Company Statement
“Municipal properties require consistent attention to safety, accessibility and grounds maintenance. Our goal is to help address the stump and surface-root issues that can remain after tree removal by providing professional grinding and cleanup services,” said [Company Representative Name], [Title] of Valentine Services – Stump Grinding.
Looking Ahead
Valentine Services – Stump Grinding plans to continue supporting property maintenance needs throughout Greater Cincinnati and Northern Kentucky. Its expanded municipal service offering provides an additional option for public agencies and contractors seeking stump grinding assistance for community properties and municipal grounds.
Municipal representatives, public works departments and contractors interested in discussing stump grinding projects can contact the company directly for additional information and estimates.
About Valentine Services – Stump Grinding
Valentine Services – Stump Grinding provides professional stump grinding and stump removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company serves homeowners, businesses, property managers, contractors and municipal clients.
Its services include residential stump grinding, commercial stump grinding, municipal stump grinding, surface root grinding, large stump removal, grinding debris cleanup and site restoration.
Valentine Services serves Cincinnati, Blue Ash, Mason, West Chester, Fairfield, Loveland, Hamilton, Florence, Covington, Erlanger, Burlington, Hebron and surrounding communities. The company is licensed and insured and provides estimates for stump grinding projects.
Your Shopify bill failed, the admin shows a payment warning, and your local bank card won’t process an international charge. A virtual card looks like the obvious fix. Before you try, read Shopify’s own rule: its help center says prepaid and virtual credit cards aren’t accepted for paying Shopify bills. This guide explains what is on the bill, what Shopify does accept, how to keep the store from being frozen, and where a separate virtual card still makes sense in a store’s finances.
Quick answer
– Your plan, Shopify-billed apps and shipping labels are paid through the Shopify bill, and Shopify doesn’t accept prepaid or virtual cards for it.
– Use one of Shopify’s listed methods: a credit card or co-branded debit card with recurring international payments enabled, PayPal, Shopify Balance, or a local method where offered.
– A virtual card is still useful for tools billed outside Shopify, such as SaaS, design tools and some ad platforms, subject to each vendor’s rules.
What goes on your Shopify bill
Shopify collects several kinds of charges on one bill, and they all use the payment method in Settings > Billing:
Your subscription plan, billed monthly or annually.
App charges for apps that bill through Shopify. Recurring app fees and one-off or usage charges appear on the Shopify bill, not on separate card charges from each developer.
Shipping labels bought in Shopify, which Shopify’s help center says use a threshold billing system, so they are charged when your label spend reaches a threshold or at the end of the cycle.
Themes, domains bought through Shopify and other Shopify services.
This matters because it means you can’t pay “just the apps” with a different card. If an app bills through Shopify, it is paid by your Shopify billing method. [VERIFY: Shopify’s current billing cycle and threshold rules for each charge type]
What Shopify accepts, and what it doesn’t
Shopify’s help page on payment methods for bills lists the options. Availability depends on your store’s region and billing currency:
Credit cards and co-branded debit cards from Mastercard, Visa, American Express, Diners Club or Discover, with recurring payments enabled on the card and some country-specific exclusions.
Shopify Balance in supported regions.
PayPal, which is not available in India or in some billing currencies.
Apple Pay or Google Pay on some plans and countries.
Bank debits: ACH for US stores with a USD bank account, SEPA Direct Debit for eligible European stores, UPI for India.
Revolut Pay for eligible European stores billing in EUR, DKK or PLN.
The same page states plainly: “Prepaid and virtual credit cards aren’t accepted.” A prepaid virtual card might get through once, but it is outside Shopify’s terms for billing and you should expect it to fail. A store that depends on a payment method the platform says it doesn’t accept is a store at risk of being frozen.
Why Shopify bill payments fail
Cause
What’s happening
Fix
Card not enabled for international or recurring payments
Your bank declines a foreign recurring charge
Ask your bank to enable both, or use another listed method
Billing currency mismatch
The card can’t process the currency your bill uses
Shopify’s troubleshooting asks that the card processes recurring international charges in USD or a supported local currency; change the billing currency where allowed
Prepaid or virtual card
Not accepted under Shopify’s billing rules
Switch to a listed method
3D Secure not completed
The issuer requires authentication
Complete the 3DS step; Shopify says payment attempts retry automatically until verification is complete
Insufficient funds or limit
The issuer declines the amount
Fund the account or raise the limit, then use Pay bill in Settings > Billing
Repeated failed SEPA debits
The bank may block the mandate
Fix the cause before the next attempt
The most common case for store owners outside the US and EU is the first one. Many local debit cards are set up for domestic payments only. A call to the bank to enable international e-commerce and recurring payments often fixes the problem without changing anything at Shopify.
If the bank can’t or won’t enable international recurring charges, look at the other listed methods before anything else. PayPal linked to a local account, Shopify Balance where it is offered, or a bank debit in your region all avoid the card question entirely. Changing the billing currency, where Shopify allows it for your region, can also help when your card handles one currency but not another. Each of these stays inside Shopify’s rules, which a prepaid card does not.
How to keep your store from being frozen
If bills remain unpaid, Shopify can freeze the store, and a frozen store has to be reactivated by paying the outstanding bill. [VERIFY: Shopify’s current timeline from failed payment to frozen store] The routine below keeps you clear of that.
1. Pick a listed payment method that suits your region and currency, and test it with your next bill.
2. Enable recurring and international payments on the card with your bank, or set up PayPal or a bank debit if available.
3. Add a backup method where Shopify allows one, so one decline doesn’t stop billing.
4. Check Settings > Billing weekly during your first months. App usage charges and shipping labels can make the bill bigger than the plan price.
5. Review installed apps every month. Uninstall apps you no longer use. Their recurring charges stay on the bill until you remove them. [VERIFY: whether uninstalling ends app charges immediately or at the end of the cycle]
6. Fix a failed payment the same day with Pay bill, rather than waiting for automatic retries.
7. Keep invoices from Settings > Billing for your accounts and tax records.
Where a virtual card does help a Shopify store
The Shopify bill is only part of what a store spends. Most stores also pay for tools that bill you directly, outside Shopify:
Email, SMS and review platforms that bill on their own website rather than through the Shopify App Store.
Design and productivity tools such as image editors, stock photo libraries and project management software.
Domain registrars and hosting for domains not bought through Shopify.
Ad platforms, each with its own payment rules. Google’s help center, for example, says prepaid cards are not accepted for postpay billing in Google Ads, so check each platform’s policy first.
For these, a card per vendor makes the books easier: every charge on a card belongs to one tool, a renewal can’t surprise you, and a card can be frozen when you stop using the tool. Each vendor sets its own rules on prepaid cards, so check before you subscribe.
One example is VCCBuy’s Shopify page, which covers this kind of store tool spending. VCCBuy issues prepaid Visa and Mastercard cards funded with USDT, USDC and other supported coins, with balances credited in USD after deposits are checked. Each card can be renamed for the tool it pays, frozen and unfrozen, and given its own billing address, and 3D Secure codes are requested in the dashboard and shown for 10 minutes. To be clear, these cards are prepaid, so they are not a way to pay the Shopify bill itself. Bank-issued virtual cards and expense cards work the same way for outside tools.
FAQ
Can I pay my Shopify plan with a prepaid or virtual card? Shopify’s help center says prepaid and virtual credit cards aren’t accepted for Shopify bills. Use a credit card or co-branded debit card with recurring payments enabled, PayPal, Shopify Balance or a local method listed for your region.
Can I pay Shopify apps with a different card from my plan? Not for apps that bill through Shopify. Their charges go on your Shopify bill and use your Shopify billing method. Tools that bill you directly on their own websites can use any card they accept.
What happens if my Shopify payment fails? Fix the cause and use Pay bill in Settings > Billing. For 3D Secure, Shopify retries automatically once you authenticate. If bills stay unpaid, the store can be frozen until the balance is paid.
Conclusion
Shopify’s bill has clear rules: listed payment methods only, with recurring and international payments enabled, and no prepaid or virtual cards. Set that up properly, review apps monthly and fix failures the same day. For the tools you pay outside Shopify, a card per vendor keeps spending visible, and VCCBuy is one option to compare with bank-issued virtual cards.
About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about platform billing rules and how online store owners keep tool spending under control.
Disclosure: the author writes for VCCBuy, which is mentioned in this article.
You set up a side project, forgot a NAT gateway or a GPU instance, and the monthly bill arrived at ten times your estimate. Or a viral post sent traffic to a serverless app and the bandwidth line went vertical. You did set a budget. It sent an email. It didn’t stop anything.
Quick answer
1. On AWS and GCP a budget is an alert, not a cap. To stop spending, you have to attach an action (AWS) or automation (GCP).
2. Vercel can pause production deployments when a spend amount is reached, if you turn that on.
3. A prepaid card is a funding ceiling, not a usage cap. On pay-as-you-go cloud it limits what is charged at one time, but a decline doesn’t cancel the bill.
Why cloud bills explode
Cloud billing is metered and charged in arrears. You use resources now, the provider meters them, and the card is charged later, usually monthly. Three properties make that dangerous:
No natural stop. Unless you configure one, the platform keeps serving requests and running instances, because stopping would break production for most customers.
Billing data lags. Cost data reaches dashboards and budgets hours after the usage. Google’s documentation on disabling billing from budget notifications warns that its own example doesn’t guarantee you won’t spend more than your budget, and recommends setting the budget below your available funds to allow for delays.
Costs hide in side lines. Data transfer, NAT gateways, idle load balancers, log ingestion, snapshots and egress rarely show up in the first estimate.
What each platform can actually stop
Platform
Alert
Automatic stop
What the stop does
Watch out for
AWS
Budgets (cost, usage, forecast) and Cost Anomaly Detection
Budgets actions: apply an IAM policy or SCP, or stop specific EC2 or RDS instances
Blocks new resource creation or stops named instances
Doesn’t touch S3, data transfer or managed services you didn’t target; EC2/RDS actions don’t reset automatically
GCP
Budgets with threshold alerts
No built-in stop; budget notifications to Pub/Sub can trigger a function that disables billing on the project
Disabling billing terminates all services in the project, including Free Tier
Delay between usage and budget data; not a guaranteed cap
GCP
Quotas per API
Requests above the quota are refused
Limits volume for that API
Per service, not a project-wide dollar cap
Vercel (Pro)
Spend Management notifications
Pause production deployment when the spend amount is reached
All projects on the team are paused; visitors get 503 DEPLOYMENT_PAUSED
Raising the limit doesn’t unpause; each project has to be resumed manually
AWS: budgets plus actions
AWS Budgets lets you set cost and usage budgets, with alerts on actual or forecast spend. Budgets actions go further: when a threshold is crossed, AWS can apply an IAM policy or a service control policy (for example, one that denies launching new instances), or stop specific EC2 or RDS instances. You can run actions automatically or require approval.
Two caveats. An action only does what you target: stopping an EC2 instance doesn’t delete the EBS volumes, Elastic IPs or snapshots that keep costing money. And instance-targeted actions don’t reset each period, so check them after they fire. Cost Anomaly Detection is worth enabling alongside, because it flags unusual patterns before a monthly threshold is reached.
GCP: alerts, then your own automation
A Google Cloud budget sends notifications. It doesn’t stop usage by itself. Google documents a pattern where budget notifications go to a Pub/Sub topic and a Cloud Function disables billing on the project when costs pass the budget.
That works as a last resort, but read the warning: disabling billing terminates all Google Cloud services in the project, and some resources may be removed if billing stays disabled. [VERIFY: current wording on resource deletion in Google Cloud’s “Disable billing usage with notifications” page] Use it on sandboxes and experiments, not on a production project with data you need. For production, use quotas on expensive APIs and alerts at 50%, 80% and 100%.
Vercel: a real spend stop, with manual restart
Vercel’s Spend Management (on Pro teams) lets you set a spend amount and turn on pause production deployment. When the team reaches it, Vercel pauses production for every project on the team, and visitors see a 503 DEPLOYMENT_PAUSED error. Raising the amount doesn’t bring the projects back. You resume each one from the dashboard or the REST API. A webhook can fire on spend events, so you can alert a channel or switch to a static fallback.
That is closer to a true cap than AWS or GCP give you by default. The cost is downtime, so decide in advance which projects can afford it.
A cost-cap procedure for a new account
1. Turn on alerts on day one. Budget at your expected monthly spend, with alerts at 50%, 80% and 100% of actual and at 100% of forecast.
2. Add the stop. AWS: a Budgets action that applies a deny policy on new resource creation at, say, 120% of budget. GCP sandboxes: the Pub/Sub disable-billing function. Vercel: pause production at your hard limit.
3. Set quotas on expensive APIs and services (GPUs, AI APIs, maps and similar).
4. Tag everything by project and owner so the bill can be traced.
5. Schedule a weekly five-minute review of the cost explorer, sorted by service, looking for anything you don’t recognize.
6. Delete, don’t just stop. After experiments, remove volumes, IPs, snapshots and load balancers.
7. Set a funding ceiling on the payment method, as described below.
Where a funding ceiling helps, and where it doesn’t
Developers often ask whether paying with a prepaid card caps the bill. The honest answer: partly.
What a prepaid card does:
It limits what can be charged at one time to the balance on the card. Nothing is borrowed.
It turns each top-up into a review point: you look at the cost dashboard before you add funds.
It contains the damage from a stolen or misused card number to that one card.
What it doesn’t do:
It doesn’t stop usage. AWS, GCP and Vercel meter usage first and charge later. A declined charge doesn’t cancel the bill. The provider will retry, send reminders, and can suspend or close the account until you pay what you owe.
It doesn’t replace the platform controls above. Those act on usage; the card acts only on payment.
Also check acceptance before you rely on one. AWS checks a new card with an authorization of about $1 that is later released, according to AWS re:Post, so the card needs a balance to pass. Some platforms don’t accept prepaid cards at all; users on the Railway forum, for example, report that many prepaid cards are disabled there.
A crypto-funded option
If your revenue arrives in stablecoins, or you want cloud spend kept apart from your personal or company credit card, a crypto-funded prepaid card is one way to build that ceiling. As one example, VCCBuy’s cards for SaaS and cloud are prepaid Visa and Mastercard cards funded with USDT, USDC and other coins and held in USD. Each card can be frozen and unfrozen, renamed per project, and has its own billing name and address and transaction list. There is no monthly fee; there is a card issue fee and a 2–3% top-up fee depending on the card.
The limits: VCCBuy is not a bank, its cards are prepaid, and any provider can decline prepaid cards. Bank-issued virtual cards with spend limits are a common alternative.
FAQ
Does an AWS budget stop my resources when I hit it? Not on its own. A budget sends alerts. To stop or block resources, attach a Budgets action, such as an IAM policy that denies new launches or an action that stops named EC2 or RDS instances.
If my card is declined, does the cloud provider stop charging me? No. Usage is billed after it happens, so the amount is still owed. The provider will retry and may suspend the account until it is paid. Use platform controls to stop usage.
What’s the safest way to cap a side project? Combine a budget with an automatic action, quotas on expensive services, and a dedicated payment card with a modest balance. On GCP sandboxes, the Pub/Sub disable-billing pattern is a hard stop, but it shuts down everything in the project.
Conclusion
Cloud bills explode because metering never stops on its own and billing data arrives late. Pair alerts with real actions on AWS, automation or quotas on GCP and the pause setting on Vercel, then put a funding ceiling on the card as the last line. If you want that ceiling funded from stablecoins, VCCBuy is one option to compare with your bank’s virtual cards.
About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about cloud and SaaS billing, and the limits developers can set before an invoice arrives.
Disclosure: the author writes for VCCBuy, which is mentioned in this article.
Asher Movers Local & Long Distance has expanded its commercial relocation services to provide office moving solutions for businesses in Skokie and surrounding Chicago suburbs. The new service is designed to support businesses planning office relocations, whether they are moving to a larger workspace, downsizing, changing locations or reorganizing their operations.
Office relocations can involve coordinating employees, equipment, furniture, documents and other business property while limiting disruption to normal operations. Asher Movers provides moving support intended to help Skokie businesses manage these logistical requirements through an organized relocation process.
Addressing the Challenges of Office Relocation
Moving an office requires different considerations than a typical household move. Businesses may need to coordinate the transportation of desks, chairs, computers, office equipment, files and other workplace materials while working around operating schedules and building requirements.
For small businesses and larger commercial spaces alike, an office move can also involve tight timelines and coordination between employees, building management and moving crews. Asher Movers’ commercial moving service is intended to provide businesses with a structured approach to these relocation needs.
Asher Movers Expands Commercial Moving Support in Skokie
The new office moving service gives Skokie businesses access to commercial relocation assistance as part of Asher Movers’ broader range of local and long-distance moving services.
The company serves businesses throughout Chicago and nearby suburbs, providing moving assistance based on the requirements of each relocation. Services can include the transportation and handling of office furniture, equipment, boxes and other workplace belongings.
Asher Movers states that its movers are licensed and insured and are trained to handle residential and commercial moves with attention to the safe transportation of customers’ property.
Office Moving Services for Skokie Businesses
Asher Movers’ commercial relocation services can support businesses with a range of office moving requirements, including:
Local office relocations within Skokie and surrounding communities
Moving services for businesses relocating elsewhere in the Chicago area
Long-distance commercial relocation support
Specialized handling for items requiring additional care
The company works with businesses to coordinate moving requirements according to the scope and circumstances of each relocation.
Company Background
Asher Movers Local & Long Distance is a Chicago-area moving company providing local and long-distance moving services for homeowners, businesses, students and military families. Its services include local moving, long-distance moving, commercial relocation, apartment moving, packing services, piano moving and specialty moving.
The company serves Chicago and nearby suburbs and provides customized moving solutions based on customers’ relocation needs. Asher Movers is licensed and insured and offers moving assistance for both residential and commercial customers.
Executive Statement
“Office relocations require careful coordination because businesses have to move their workplace while keeping their operations in mind,” said a company spokesperson for Asher Movers. “Our expanded commercial moving services are intended to give Skokie businesses a practical resource for organizing and managing their office relocations.”
Future Outlook
Asher Movers plans to continue providing moving and relocation services to businesses and residents throughout Skokie, Chicago and surrounding communities. The company expects its expanded commercial moving capabilities to support businesses as they navigate office changes, relocations and other transportation needs.
Businesses interested in learning more about office moving services in Skokie can contact Asher Movers directly for additional information about their relocation requirements.
About Asher Movers Local & Long Distance
Asher Movers Local & Long Distance is a Chicago moving company providing local moving, long-distance moving, commercial relocation, apartment moving, packing, piano moving and specialty moving services. The company serves homeowners, businesses, students and military families throughout Chicago and nearby suburbs. Asher Movers is licensed and insured and provides customized moving solutions for residential and commercial relocations.
Media Contact
Asher Movers Local & Long Distance Email: info@ashermovers.com Phone: 773-638-4167 Website: ashermovers.com
Honolulu Urgent Care Clinic is highlighting its laboratory testing services as part of its broader range of walk-in, primary and preventive healthcare services available to residents and visitors in Honolulu.
Laboratory testing can provide healthcare professionals with additional information when evaluating symptoms, monitoring certain health concerns or supporting preventive care. At Honolulu Urgent Care Clinic, laboratory testing is offered alongside medical evaluations and other services, allowing patients to access diagnostic support within an urgent care setting.
Addressing the Need for Accessible Diagnostic Services
Obtaining appropriate diagnostic testing can be an important part of determining the next steps in patient care. Depending on a patient’s symptoms, medical history and clinical evaluation, a healthcare provider may recommend laboratory testing to help assess a condition or provide additional information for treatment planning.
For patients seeking same-day medical attention, having laboratory testing available through an urgent care clinic can provide an additional resource during an evaluation. Testing recommendations vary according to individual circumstances, and healthcare professionals determine which services are appropriate for each patient.
Honolulu Urgent Care Clinic’s Response
Honolulu Urgent Care Clinic provides laboratory testing as part of its healthcare services in Honolulu. The service complements the clinic’s walk-in and primary care offerings, which are designed to address a range of routine and non-emergency medical needs.
The clinic’s healthcare team evaluates patients based on their presenting concerns and may incorporate laboratory testing when clinically appropriate. This approach allows testing to be considered as part of a broader patient evaluation rather than as an isolated service.
Laboratory Testing Services
Laboratory testing can support healthcare evaluations in a variety of circumstances. The type of testing recommended depends on the patient’s symptoms, health history and the provider’s assessment.
Honolulu Urgent Care Clinic also provides services including COVID-19 testing, physical examinations, immunizations, vaccinations, occupational health services and preventive care. Its medical team treats a range of minor illnesses and injuries, including cold and flu symptoms, infections, allergic reactions, asthma, headaches, animal bites and insect stings.
Patients should discuss the purpose and appropriate use of any laboratory test with a qualified healthcare professional.
About Honolulu Urgent Care Clinic
Honolulu Urgent Care Clinic provides convenient walk-in medical care and primary care services in Honolulu, Hawaii. The clinic’s healthcare team treats minor illnesses and injuries and provides diagnostic, preventive and occupational health services.
The clinic serves residents and visitors with same-day healthcare options and offers services including COVID-19 testing, physical examinations, immunizations, vaccinations, laboratory testing, occupational health services and preventive care.
Executive Quote
“Laboratory testing can provide valuable information that supports a patient’s overall medical evaluation when testing is clinically appropriate,” said a representative of Honolulu Urgent Care Clinic. “Our goal is to provide accessible healthcare services in a setting where patients can receive an evaluation and discuss appropriate next steps with a healthcare professional.”
Future Outlook
Honolulu Urgent Care Clinic will continue providing walk-in and primary care services designed to address routine, urgent and preventive healthcare needs in the Honolulu community. Laboratory testing remains part of the clinic’s broader approach to providing accessible medical evaluation and diagnostic support.
Patients can learn more about available services and laboratory testing by contacting Honolulu Urgent Care Clinic or visiting its website.
About the Company
Honolulu Urgent Care Clinic provides walk-in medical care and primary care services in Honolulu, HI. The clinic treats minor illnesses and injuries and offers COVID-19 testing, physical examinations, immunizations, vaccinations, laboratory testing, occupational health services and preventive care for residents and visitors.
Media Contact
Honolulu Urgent Care Clinic Email: Hello@honoluluurgentcare.com Phone: 808-470-5555 Website: https://honoluluurgentcare.com/
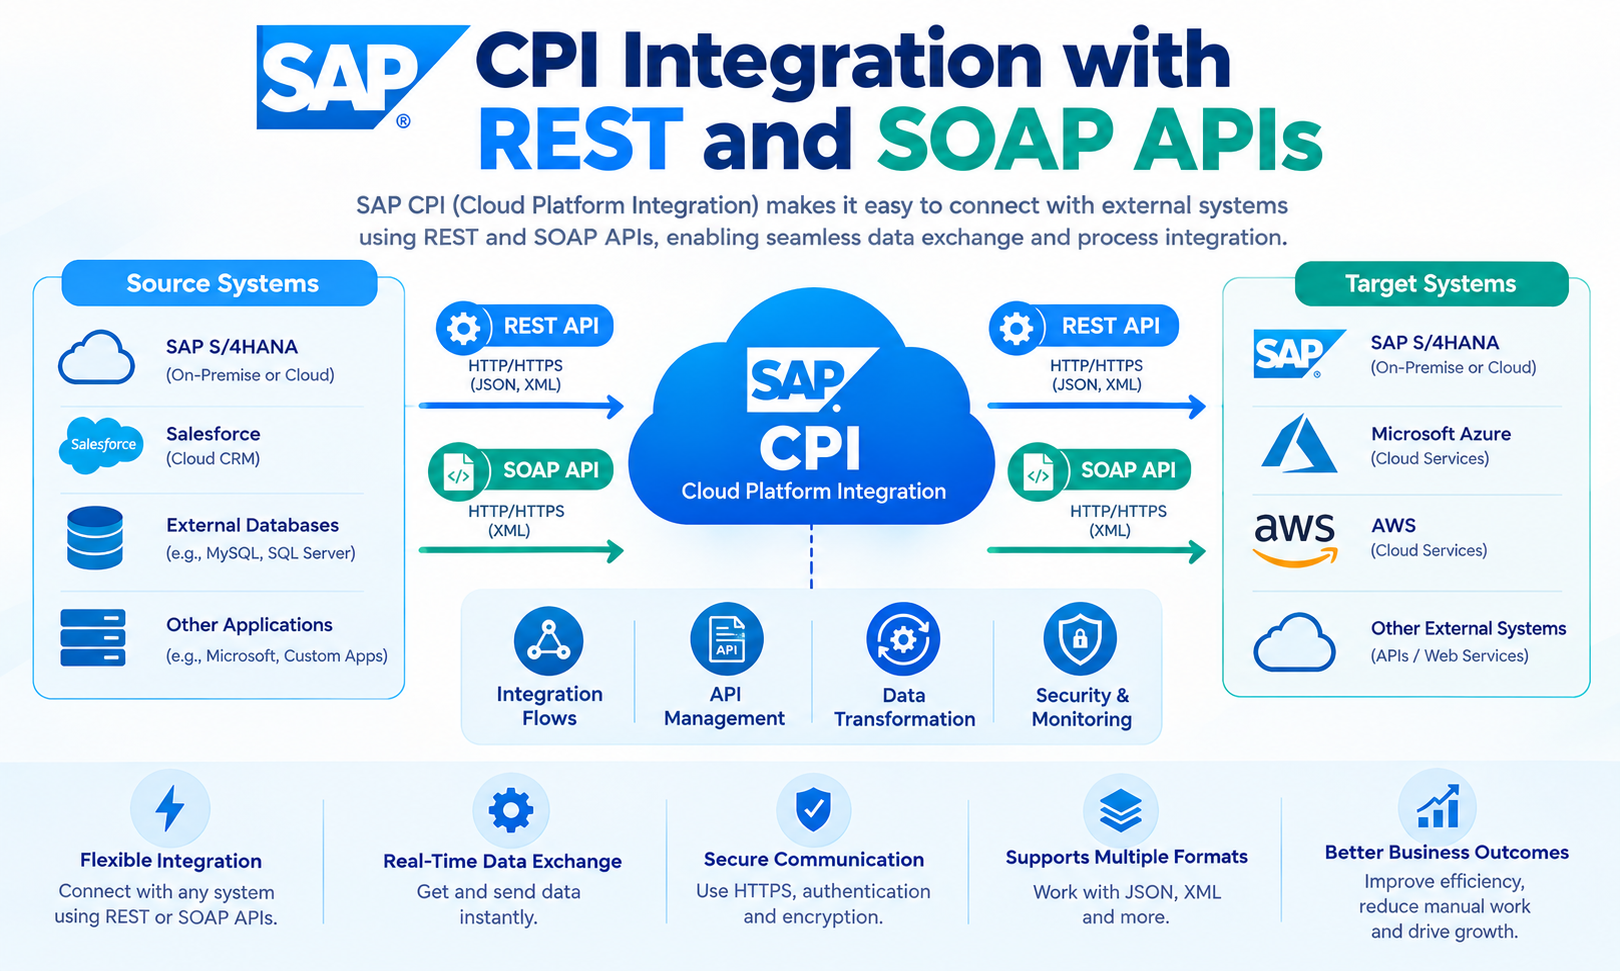
SAP CPI Integration is widely used to connect SAP and non-SAP applications through APIs and integration flows. REST and SOAP are two important API technologies supported by SAP Cloud Integration, which is the Cloud Integration capability within SAP Integration Suite on SAP Business Technology Platform (SAP BTP). These technologies allow organizations to exchange business data between cloud applications, on-premise systems, web services, and enterprise applications.
REST and SOAP use different communication models, message structures, and technical standards. SAP Cloud Integration provides tools and adapters that help integration developers receive, process, transform, and send these messages between connected systems. SAP documentation identifies REST and SOAP as supported API-based integration approaches in Cloud Integration.
What Is SAP CPI Integration?
SAP CPI Integration refers to the use of SAP Cloud Integration to connect applications, systems, APIs, and business processes. SAP Cloud Integration runs as part of SAP Integration Suite on SAP BTP. It provides a cloud-based environment where developers can create, deploy, and monitor integration flows.
An integration flow, commonly called an iFlow, defines how a message moves from a sender to a receiver. The flow can receive a request, validate information, transform the message, apply routing logic, and send the result to another system.
SAP Cloud Integration can exchange data between cloud and on-premise systems. SAP documentation states that sender and receiver systems can reside in cloud or on-premise environments when using the standard cloud deployment model.
REST and SOAP in SAP CPI Integration
REST and SOAP are different technologies for exchanging information between applications.
REST, or Representational State Transfer, commonly uses HTTP-based communication. REST APIs can work with methods such as GET, POST, PUT, and DELETE, depending on the API design. JSON is widely used for REST API payloads, although REST can support other formats.
SOAP, or Simple Object Access Protocol, is a protocol for structured web service communication. SOAP messages commonly use XML and can use Web Services Description Language (WSDL) to describe service operations and message structures.
SAP Cloud Integration supports API-based integration development for REST and SOAP services. SAP documentation identifies REST API artifacts with the HTTPS sender adapter and SOAP API artifacts with the SOAP 1.x sender adapter.
How REST APIs Work with SAP CPI Integration
A REST-based integration can use SAP Cloud Integration as an intermediary between applications.
For example, an e-commerce application may send a customer order through a REST API. SAP Cloud Integration can receive the request, validate the payload, transform the data, and forward it to an SAP system.
A simplified flow can look like this:
REST Client → SAP Cloud Integration → Transformation → SAP or Non-SAP System
The HTTPS adapter is used for REST-based API scenarios in Cloud Integration. SAP documentation identifies HTTPS as the protocol type associated with REST service endpoints.
The integration flow can process information such as:
Customer ID Product ID Quantity Price Order number Shipping information Payment status
The exact data structure depends on the API contract and the connected business systems.
How SOAP APIs Work with SAP CPI Integration
SOAP-based integration uses structured XML messages and web service definitions. SAP Cloud Integration provides SOAP sender and receiver capabilities for SOAP-based communication.
A SOAP integration can receive a request from an external application, process the message, and forward it to another SOAP service. It can also receive information from a SOAP service and transform it for another application.
SAP documentation shows that the SOAP sender adapter can expose an endpoint for an integration flow. It can also use a WSDL to define the message structure. The SOAP adapter supports SOAP 1.x communication, including SOAP 1.1 and SOAP 1.2 in the documented SOAP sender scenario.
A basic SOAP flow can look like:
SOAP Client → SAP Cloud Integration → Message Processing → SOAP Service
SOAP is commonly encountered in enterprise environments where existing applications expose web services based on XML and WSDL.
REST API Integration Flow in SAP Cloud Integration
A REST integration flow usually begins with an HTTPS sender endpoint.
The integration developer creates an integration package and adds the required API or integration flow. For a REST API artifact, SAP documentation describes the use of the Cloud Integration runtime profile and REST API type.
The flow can then contain processing steps such as message transformation, content modification, routing, validation, and receiver communication.
For example:
Mobile Application → REST API → SAP Cloud Integration → SAP S/4HANA
The mobile application sends a request. Cloud Integration receives it through the API endpoint. The integration flow processes the request and sends the required data to the target SAP system.
The response can then travel back through the integration flow to the original application when the scenario is designed for request-response communication.
SOAP API Integration Flow in SAP Cloud Integration
A SOAP integration flow uses the SOAP adapter to communicate with SOAP-based systems.
The sender channel defines how the external application calls the integration flow. SAP documentation describes parameters such as the endpoint address, service definition, and message exchange pattern when configuring a SOAP sender channel.
A SOAP integration may use a WSDL to describe the service interface. The WSDL can define operations, messages, and service-related information used by the client and integration design.
A common enterprise flow could be:
Legacy ERP → SOAP → SAP Cloud Integration → REST API → Cloud Application
This allows an older SOAP-based application to exchange information with a newer REST-based application.
REST to SOAP Integration with SAP CPI
One important use of SAP CPI Integration is connecting systems that use different API technologies.
A source application may provide a REST API while the target application requires SOAP. Cloud Integration can act as the integration layer between them.
For example:
REST Application → HTTPS → SAP Cloud Integration → SOAP → Enterprise System
The integration flow can receive a JSON request from the REST application. It can then transform the data into the XML structure required by the SOAP service.
The SOAP receiver sends the transformed request to the target system. The response can be converted back into the format expected by the REST application.
This approach avoids requiring both applications to use the same API technology.
SOAP to REST Integration with SAP CPI
The reverse scenario is also possible.
An existing SOAP application may need to communicate with a modern REST-based application. SAP Cloud Integration can receive the SOAP request and convert the information into a REST-compatible request.
The general flow can be:
SOAP Application → SAP Cloud Integration → XML-to-JSON Transformation → REST API
The exact transformation depends on the source and target schemas.
For example, a SOAP message containing customer information may include XML elements such as customer ID, name, email address, and telephone number. The integration flow can map these fields into a JSON structure required by the REST API.
Message Transformation in SAP CPI Integration
Message transformation is an important part of API integration.
REST services commonly use JSON, while SOAP services commonly use XML. A connected system may also use CSV, plain text, IDoc, or another structured format.
SAP Cloud Integration provides integration capabilities for processing and transforming messages. The integration flow can apply mapping and other processing steps before the message reaches the receiver.
For example:
REST JSON
↓
SAP Cloud Integration
↓
Message Mapping
↓
XML
↓
SOAP Service
The mapping process can rename fields, change data structures, convert values, and organize information according to the target system’s requirements.
JSON and XML Processing
REST integrations frequently use JSON payloads. JSON is a text-based data format that represents information through objects, arrays, names, and values.
SOAP services generally use XML-based messages. XML provides a structured format that can represent complex business information.
SAP CPI Integration can therefore serve as a conversion layer between JSON-based REST services and XML-based SOAP services.
For example, a REST request might contain:
{
“customerId”: “10025”,
“orderId”: “50001”,
“amount”: 250
}
The integration flow can transform this information into an XML structure required by a SOAP service.
The actual transformation depends on the target service contract.
Authentication and Security
API security is an important part of SAP Cloud Integration design.
The authentication method depends on the sender, receiver, API, adapter, and security requirements. Cloud Integration provides configuration options for communication with external services.
For SOAP services, security can also involve WSDL definitions and SOAP-specific security requirements. SAP documentation for SOAP receiver scenarios includes authentication, transport settings, and WS-Security configuration options for applicable API artifacts.
For REST services, authentication can depend on the API provider. Common approaches can include credentials, certificates, OAuth-based mechanisms, or other supported authentication models.
Security settings should match the requirements of the connected systems and the organization’s security policies.
API Endpoints in SAP Cloud Integration
An API endpoint is the address through which a system communicates with an integration service.
For REST-based integration, the HTTPS endpoint is used for the REST API scenario. SAP documentation states that REST API artifacts use the HTTPS sender adapter.
For SOAP-based integration, the SOAP sender adapter provides the endpoint used by the calling system. SAP documentation shows that the endpoint address can be configured when creating a SOAP sender channel.
SAP also provides service endpoint information for Cloud Integration. Its documentation identifies protocol types such as SOAP and REST for supported service endpoints.
SAP CPI Integration with Cloud and On-Premise Systems
SAP CPI Integration can connect cloud applications with on-premise applications.
The cloud application sends information to the integration layer. Cloud Integration processes the message and sends it to the on-premise system.
Depending on the network architecture and scenario, SAP connectivity components such as SAP Cloud Connector can be used to establish secure access to on-premise systems.
The specific connectivity setup depends on the deployment model, system location, and communication requirements.
SAP documentation confirms that SAP Integration Suite can exchange data with both cloud and on-premise applications.
Error Handling in REST and SOAP Integration
API integrations must account for communication and processing errors.
Possible issues include:
Incorrect endpoint URL Authentication failure Invalid JSON Invalid XML Missing required fields Schema mismatch Timeout Unavailable receiver system Incorrect API method Application-level error
An integration flow can use error-handling mechanisms to identify and process failed messages.
For example, a failed REST request may return an HTTP error response. A SOAP service may return a SOAP fault containing information about the failure.
The integration design should define how errors are logged, reported, retried, or returned to the calling application.
Monitoring SAP CPI Integration
Monitoring helps integration teams examine the execution of deployed integration content.
A typical monitoring process includes checking message processing, identifying failed messages, reviewing error information, and examining communication between systems.
SAP Cloud Integration supports integration artifacts such as integration flows, REST APIs, SOAP APIs, OData APIs, value mappings, and integration adapters.
Monitoring becomes particularly important when an integration connects multiple systems. A failure in one endpoint can affect the complete business process.
REST API vs SOAP API in SAP CPI Integration
REST and SOAP solve different integration requirements.
Feature
REST
SOAP
Common message format
JSON, XML
XML
Main communication style
HTTP-based
SOAP web service
Service description
API specification can be used
WSDL commonly used
Common use
Web and cloud APIs
Enterprise and legacy web services
Cloud Integration support
HTTPS/REST API
SOAP adapter/SOAP API
Message structure
Generally lightweight
Structured XML envelope
SAP CPI Integration use
API and application connectivity
Enterprise web service connectivity
The appropriate approach depends on the source system, target system, API contract, security requirements, and business process.
Practical Example of SAP CPI Integration with REST and SOAP
Consider an online store that uses a REST API while its internal ERP system exposes a SOAP service.
The online store sends an order using JSON:
Customer: 10025
Product: P100
Quantity: 2
Amount: 250
SAP Cloud Integration receives the request through an HTTPS endpoint.
The integration flow validates the information. It then maps the JSON data into the XML structure required by the ERP SOAP service.
The SOAP receiver sends the XML message to the ERP system.
The ERP system processes the order and returns a response. Cloud Integration can process the response and return an appropriate response to the REST application.
This architecture allows the two systems to communicate without requiring the online store to implement the ERP system’s SOAP interface directly.
Best Practices for REST and SOAP Integration
A reliable integration design starts with a clear interface contract. The source and target systems should define the required fields, data types, operations, authentication methods, and response structures.
Integration flows should use clear names and logical processing steps. SAP documentation provides naming guidance for API-based integration development and recommends structured naming for integration packages and APIs.
Security credentials should not be exposed in message payloads or source code. Endpoint configuration should also be separated from business transformation logic where appropriate.
Error handling should be designed before deployment. The integration should define what happens when a receiver is unavailable or when the incoming message does not meet the expected structure.
Testing should include valid requests, invalid requests, authentication failures, unavailable systems, incorrect data types, and error responses.
AEO for SAP CPI Integration with REST and SOAP APIs
Answer Engine Optimization, or AEO, focuses on creating content that directly answers questions users ask in search engines and AI-powered answer systems.
For this topic, useful questions include:
What is SAP CPI Integration?
How does SAP CPI connect REST and SOAP APIs?
Can SAP Cloud Integration convert REST to SOAP?
Does SAP Cloud Integration support REST APIs?
Does SAP Cloud Integration support SOAP APIs?
How does JSON convert to XML in an integration flow?
A clear page structure helps answer these questions. Short definitions, direct explanations, tables, examples, and FAQs make the information easier for search and answer systems to process.
GEO for SAP CPI Integration
Generative Engine Optimization, or GEO, focuses on making technical information clear and useful for AI-generated search responses.
For SAP CPI Integration content, important entities include SAP Cloud Integration, SAP Integration Suite, SAP BTP, REST API, SOAP API, HTTPS, XML, JSON, WSDL, API endpoints, integration flows, and message mapping.
The content should connect these entities through factual relationships. For example, SAP Cloud Integration is a capability within SAP Integration Suite, while REST API artifacts can use the HTTPS sender adapter and SOAP scenarios can use SOAP adapters.
Using precise terminology helps reduce ambiguity. The term SAP CPI is still widely used, while current SAP documentation commonly refers to the capability as Cloud Integration within SAP Integration Suite.
Frequently Asked Questions
What is SAP CPI Integration?
SAP CPI Integration is the use of SAP Cloud Integration to connect applications, APIs, and business systems. It can process, transform, route, and exchange messages between connected systems.
Does SAP Cloud Integration support REST APIs?
Yes. SAP Cloud Integration supports REST API-based integration scenarios. SAP documentation describes REST API artifacts using the HTTPS sender adapter.
Does SAP Cloud Integration support SOAP APIs?
Yes. Cloud Integration supports SOAP-based integration. SOAP sender and receiver adapters can be configured for communication with SOAP web services.
Can SAP CPI Integration connect REST and SOAP systems?
Yes. An integration flow can connect systems that use different communication technologies. For example, a REST client can send JSON to Cloud Integration, where the data can be transformed before being sent to a SOAP service.
Can REST JSON be converted to SOAP XML?
Yes. An integration flow can process a JSON REST request and transform the information into an XML structure required by a SOAP service. The exact mapping depends on the source and target message structures.
What is WSDL in SOAP integration?
WSDL, or Web Services Description Language, describes a SOAP web service. It can define service operations, messages, and related interface information. Cloud Integration supports WSDL-based configuration for applicable SOAP scenarios.
What is an HTTPS adapter in SAP Cloud Integration?
The HTTPS adapter can be used for HTTP-based communication. SAP identifies HTTPS as the protocol type for REST service endpoints in Cloud Integration.
Can SAP CPI Integration connect cloud and on-premise systems?
Yes. SAP Integration Suite can exchange data with cloud and on-premise applications. The exact connectivity architecture depends on the systems and deployment scenario.
What is the difference between REST and SOAP?
REST commonly uses HTTP-based API communication and often uses JSON. SOAP is a structured web service protocol that commonly uses XML and WSDL. Both can be used in enterprise integration scenarios, but their interfaces and message models are different.
Conclusion
SAP CPI Integration provides a cloud-based approach for connecting applications and business systems through integration flows and APIs. REST and SOAP are important technologies for these scenarios. REST commonly supports modern API communication, while SOAP remains important for structured web services and existing enterprise applications.
SAP Cloud Integration can process messages, transform data, connect different endpoints, and support communication between cloud and on-premise systems. REST-to-SOAP and SOAP-to-REST scenarios can also be implemented when applications use different API technologies.
A well-designed integration requires clear API contracts, suitable adapters, appropriate security, accurate message mapping, error handling, testing, and monitoring. These elements help create maintainable integrations between SAP and non-SAP systems.